Can targeted reforms at home save India from external shocks?
The Indian economy, to quote from Charles Dickens’ novel, looks like A Tale of Two Cities. Recent estimates suggest India’s real GDP expanded by 7.8% in the January-March quarter (Q4) of FY26, with strong growth noted across sectors — from services (9.3%) to manufacturing (10.7%) and construction (7.4%).
Consumption expenditure, which is the largest component (58%) of GDP, also grew at around 7.6%, pointing to the resilience of the Indian economy. Other macro indicators such as goods and services tax (GST) collections, sales of automobiles, two-wheelers, and FMCG products complement the healthy growth in consumption expenditure. The gross GST collections grew around 7.7% in Q4 of FY26, sales of passenger vehicles rose 17%, two-wheelers increased 25%, and FMCG products posted 12% growth — the highest since June 2022.
External pressure
Yet all is not well on the external front.
The Indian rupee is depreciating against the US dollar, the current account deficit (CAD) is widening, and net foreign direct investment (FDI) is falling. Interestingly, rupee’s fall is not a recent phenomenon. Between 2005 and 2024, the Indian currency has, on average, depreciated around 3.5% annually. An analysis of long-term data suggests that the average annual depreciation of the rupee was 0.4% between 2000 and 2004.
The depreciation accelerated significantly after that, with the rupee on average falling 3.4% annually between 2005 and 2014. This trend remained largely unchanged between 2015 and 2025, with the rupee on average depreciating 3.5% annually.
However, what is worrying is that in recent times, the depreciation of the rupee has broken all earlier records. Among countries that are on a flexible exchange rate and not on a managed or fixed float — for example, Japanese yen
(6.6%), South Korean won (7%), Indonesian rupiah (9.3%), and the Philippine peso (10.3%), to name a few — the Indian rupee has depreciated the most over the last one year by around 11.2%.
Net FDI inflow is also falling. Recent estimates from the Reserve Bank of India (RBI) suggest that the total amount of dollars flowing out of the country exceeded inflows by USD30.8 billion in FY26, a more than six-fold increase over FY25. India witnessed a balance of payments (BoP) surplus as recently as FY23 but took a hit, falling into the negative territory from FY24 onwards. The data for FY26 is until December 2026, with a worsening trend as the Iran-Israel-US war continues, starting February 2026.
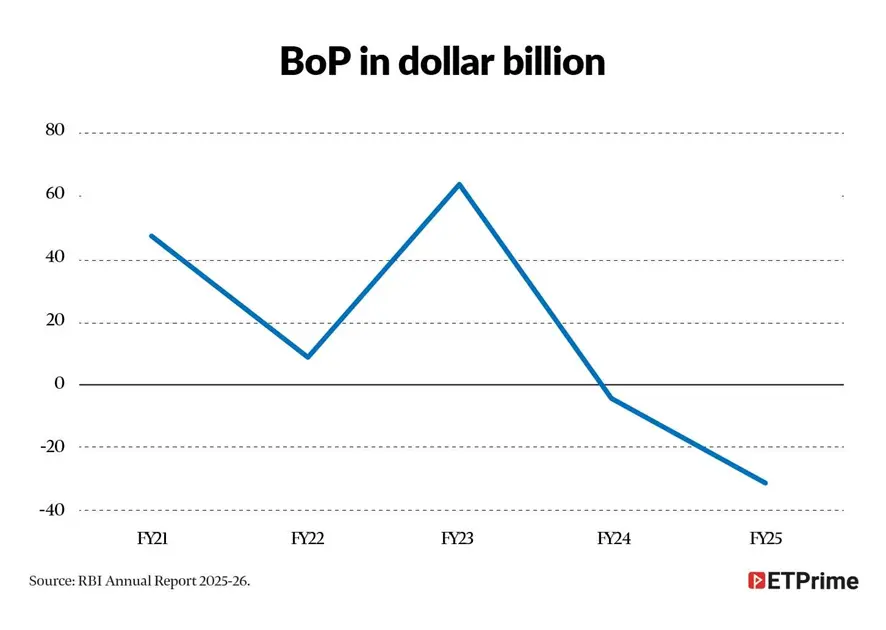
BoP is the sum of the current account and the capital account. The current account captures surpluses or deficits in
tradable items, while the capital account records investment flows (both direct and portfolio investments), external borrowings, and asset transfer. Over the last five years, any gap owing to trade deficits was largely financed by the surplus in services trade. India has been importing crude oil worth USD130 billion—USD150 billion annually, and a significant portion of this import bill has been financed by the surplus in services, which has averaged over USD240 billion during the past three years. For instance, during FY25, India’s overall merchandise trade deficit stood at USD251.6 billion in FY25, down from USD286.9 billion in the previous year.
However, this trend has changed in 2026. There are two major reasons.
#1. The Indian stock market has been on a downward trend.
FPI (foreign portfolio investment) outflows have been to the tune of INR2 lakh crore in FY26. The recent emergence of agentic AI models has raised concerns about the future of Indian software exports, which no longer appear as promising as before. Meanwhile, the US and Taiwanese stock markets are attracting renewed investor interest, driven by strong performance in microchip and AI stocks.
#2. The war in West Asia has also led to higher prices for crude oil, fertilizers, and chemical products, adversely impacting India’s external sector performance measured in terms of BoP.
The war and the higher import price have led to dollar appreciating against the rupee, further worsening the CAD. India currently imports almost 90% of its energy requirement. So, every USD10 rise in global Brent crude prices is estimated to widen India’s CAD by about 0.3% to 0.5% of GDP, translating to billions of dollars.
Brent crude was trading between USD66-USD70 per barrel before the start of the war in February 2026, reaching a high of USD126 on April 29, 2026. Now, with the UAE’s exit from OPEC (Organization of the Petroleum Exporting Countries), Brent crude may continue to hover around USD80 a barrel for the remainder of 2026, even if Iran and the US decide to end the war. If the disruption persisted through the rest of 2026, Brent could average USD91 per barrel in the fourth quarter of 2026.
The final cut
Returning to the tale of two cities — for the Indian economy, the more consequential headwinds appear to be largely exogenous: geopolitical conflicts and the structural disruption led by AI-driven automation, both of which lie beyond the government’s direct control.
Where the government does have meaningful control, however, is in creating conditions that attract sustained FPI inflows, and make India a better place to do business. For instance, at last Friday’s monetary policy meeting, the RBI outlined measures to simplify access for overseas investors to government bonds and equities. Separately, the government announced a reduction in capital gains taxes on bond investments by FPIs.
The last time the Indian government initiated a bold reform was on September 20, 2019, when it executed the largest corporate tax reduction in three decades — slashing the base corporate income tax rate for domestic companies from 30% to 22%. The move, introduced by finance minister Nirmala Sitharaman, was aimed at boosting domestic investment and reviving economic growth.
However, larger corporations largely used the windfall not to reinvest within India, but to acquire foreign assets abroad. Corporate investment, by and large, remained subdued.
This time, the focus needs to shift toward more targeted interventions — extending tax benefits or introducing interest subvention schemes for the MSME sector, strengthening incentives for setting up global capability centers (GCCs), and deepening support for India’s startup ecosystem.
Unlike the exogenous pressures of geopolitical conflict and AI-driven disruption, these are the policy measures that are firmly within the government’s control, and the onus is on it to deploy them wisely.(The author is professor, Mahindra University)
